Free guide · PDF · 13 pages
High & Ultra-High Net Worth Guide
How lenders assess complex wealth, private banks, structuring large loans and the 2026 tax landscape.
Read onlineAbove £1 million, lending decisions are made by people rather than by formula. Private banks and specialist lenders look at the whole of your position: income, assets, liquidity and plans. We present that picture properly and negotiate terms on your behalf.
We have access to private banks and specialist lenders as well as the high street and know which will suit a given set of circumstances.
Access to lenders that assess each case on its merits, some of which do not deal with the public directly.
Bonuses, carried interest, dividends, trust income and overseas earnings set out clearly for the underwriter.
Interest-only, part-and-part and offset arrangements, with repayment strategies that lenders will accept.
Rates, fees and conditions on larger loans are often open to negotiation. We negotiate them.
Illustrative examples of the situations we are asked to help with. They are not accounts of individual clients.
A purchaser of a £3 million home who wishes to keep capital invested rather than repay it monthly.
We approach lenders comfortable with interest-only at that level and document a repayment strategy they will accept.A partner whose income is largely an annual profit share that varies from year to year.
We place the case with a lender that will take an averaged or longer-term view of earnings.A listed country house with land, outbuildings and unusual construction.
We select lenders and valuers experienced with property of that kind before an application is made.A client with a substantial investment portfolio, offered better terms by a private bank in return for placing part of it under the bank's management.
We compare the private bank's assets under management requirement with offers from specialist lenders that do not ask for one, so you can judge whether the relationship is worth it.The Intermediary reported on finance arranged by Artillium for the purchase of a Churchill mansion.
Read the article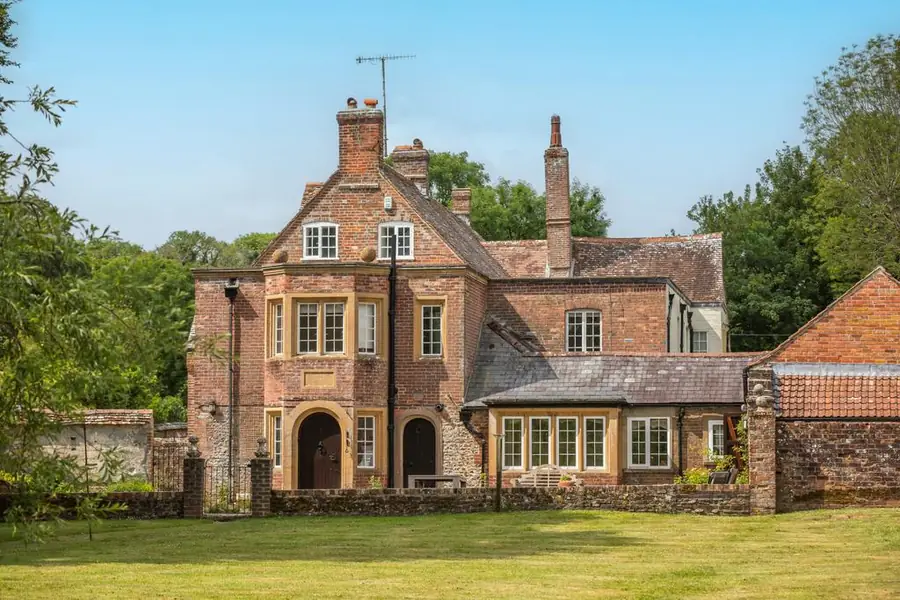
 30 July 2026
Not always. Some high street and specialist lenders offer large loans and the right choice depends on your circumstances. We compare them.
Some private banks ask for assets to be placed under their management as a condition of lending; others do not. We tell you which at the outset.
Often, at lower loan-to-value levels and with a credible repayment strategy such as the sale of assets, investments or the property itself.
Larger and more complex cases can take longer than a standard mortgage. We give you a realistic timetable at the start and manage it closely.
It varies with the lender, the property and the borrower. We will indicate what is realistic once we understand your position.
Related reading: High & Ultra-High Net Worth Guide · Vested Shares & RSU Mortgage Guide · Mortgage calculators
Reviewed by Thomas Boughton CeMAP, October 2026.
How lenders and private banks approach complex wealth, larger loans and share-based pay.
How lenders assess complex wealth, private banks, structuring large loans and the 2026 tax landscape.
Read online
How lenders count RSUs and vested shares, the evidence they need, tax at vest and using shares towards a deposit.
Read onlineTell us about the property and how your income and assets are held. The first conversation is without obligation.
Your home may be repossessed if you do not keep up repayments on your mortgage. Lending is subject to status, lender criteria and individual circumstances.